Home Insurance · Norman, OK
Does Your Home Insurance Actually Hold Up in an Oklahoma Storm?
Hail, straight-line wind, tornadoes, and a burst pipe in February. Most insurance guides are written for an average state. We write policies for this one, from an office on Wall Street in Norman.
20–30%
typical savings when home and auto are bundled
Dwelling, belongings, liability, and loss of use, with wind and hail deductibles built for Oklahoma weather.
A home policy protects the dwelling itself plus everything inside it. That is the simple version. The useful version is knowing how your wind and hail deductible is set, whether your roof is covered at replacement cost, how much liability you carry, and where you and your family would live for up to 24 months if the house were unlivable.
We review each of those with every homeowner before a storm ever rolls through, and we stay on the phone with you after one does.
What it covers
What does a home insurance policy cover?
Dwelling
The structure of your home, from the foundation to the roof, and attached structures like a garage.
Personal property
Furniture, electronics, clothing, and the rest of what is inside, at home or temporarily away from it.
Liability and guest medical
If a guest is injured on your property or you are held responsible for damage to someone else, liability pays the claim and the legal defense. Guest medical pays smaller medical bills without a lawsuit.
Additional living expense (loss of use)
If a fire or storm makes the house unlivable, this pays for a rental, hotel, or short-term stay while it is rebuilt, for up to 24 months.
Split deductibles
Oklahoma policies typically carry one deductible for all perils and a separate one for wind and hail. We explain both so there are no surprises after a hailstorm.
Other structures
Detached garages, storm shelters, fences, and workshops.
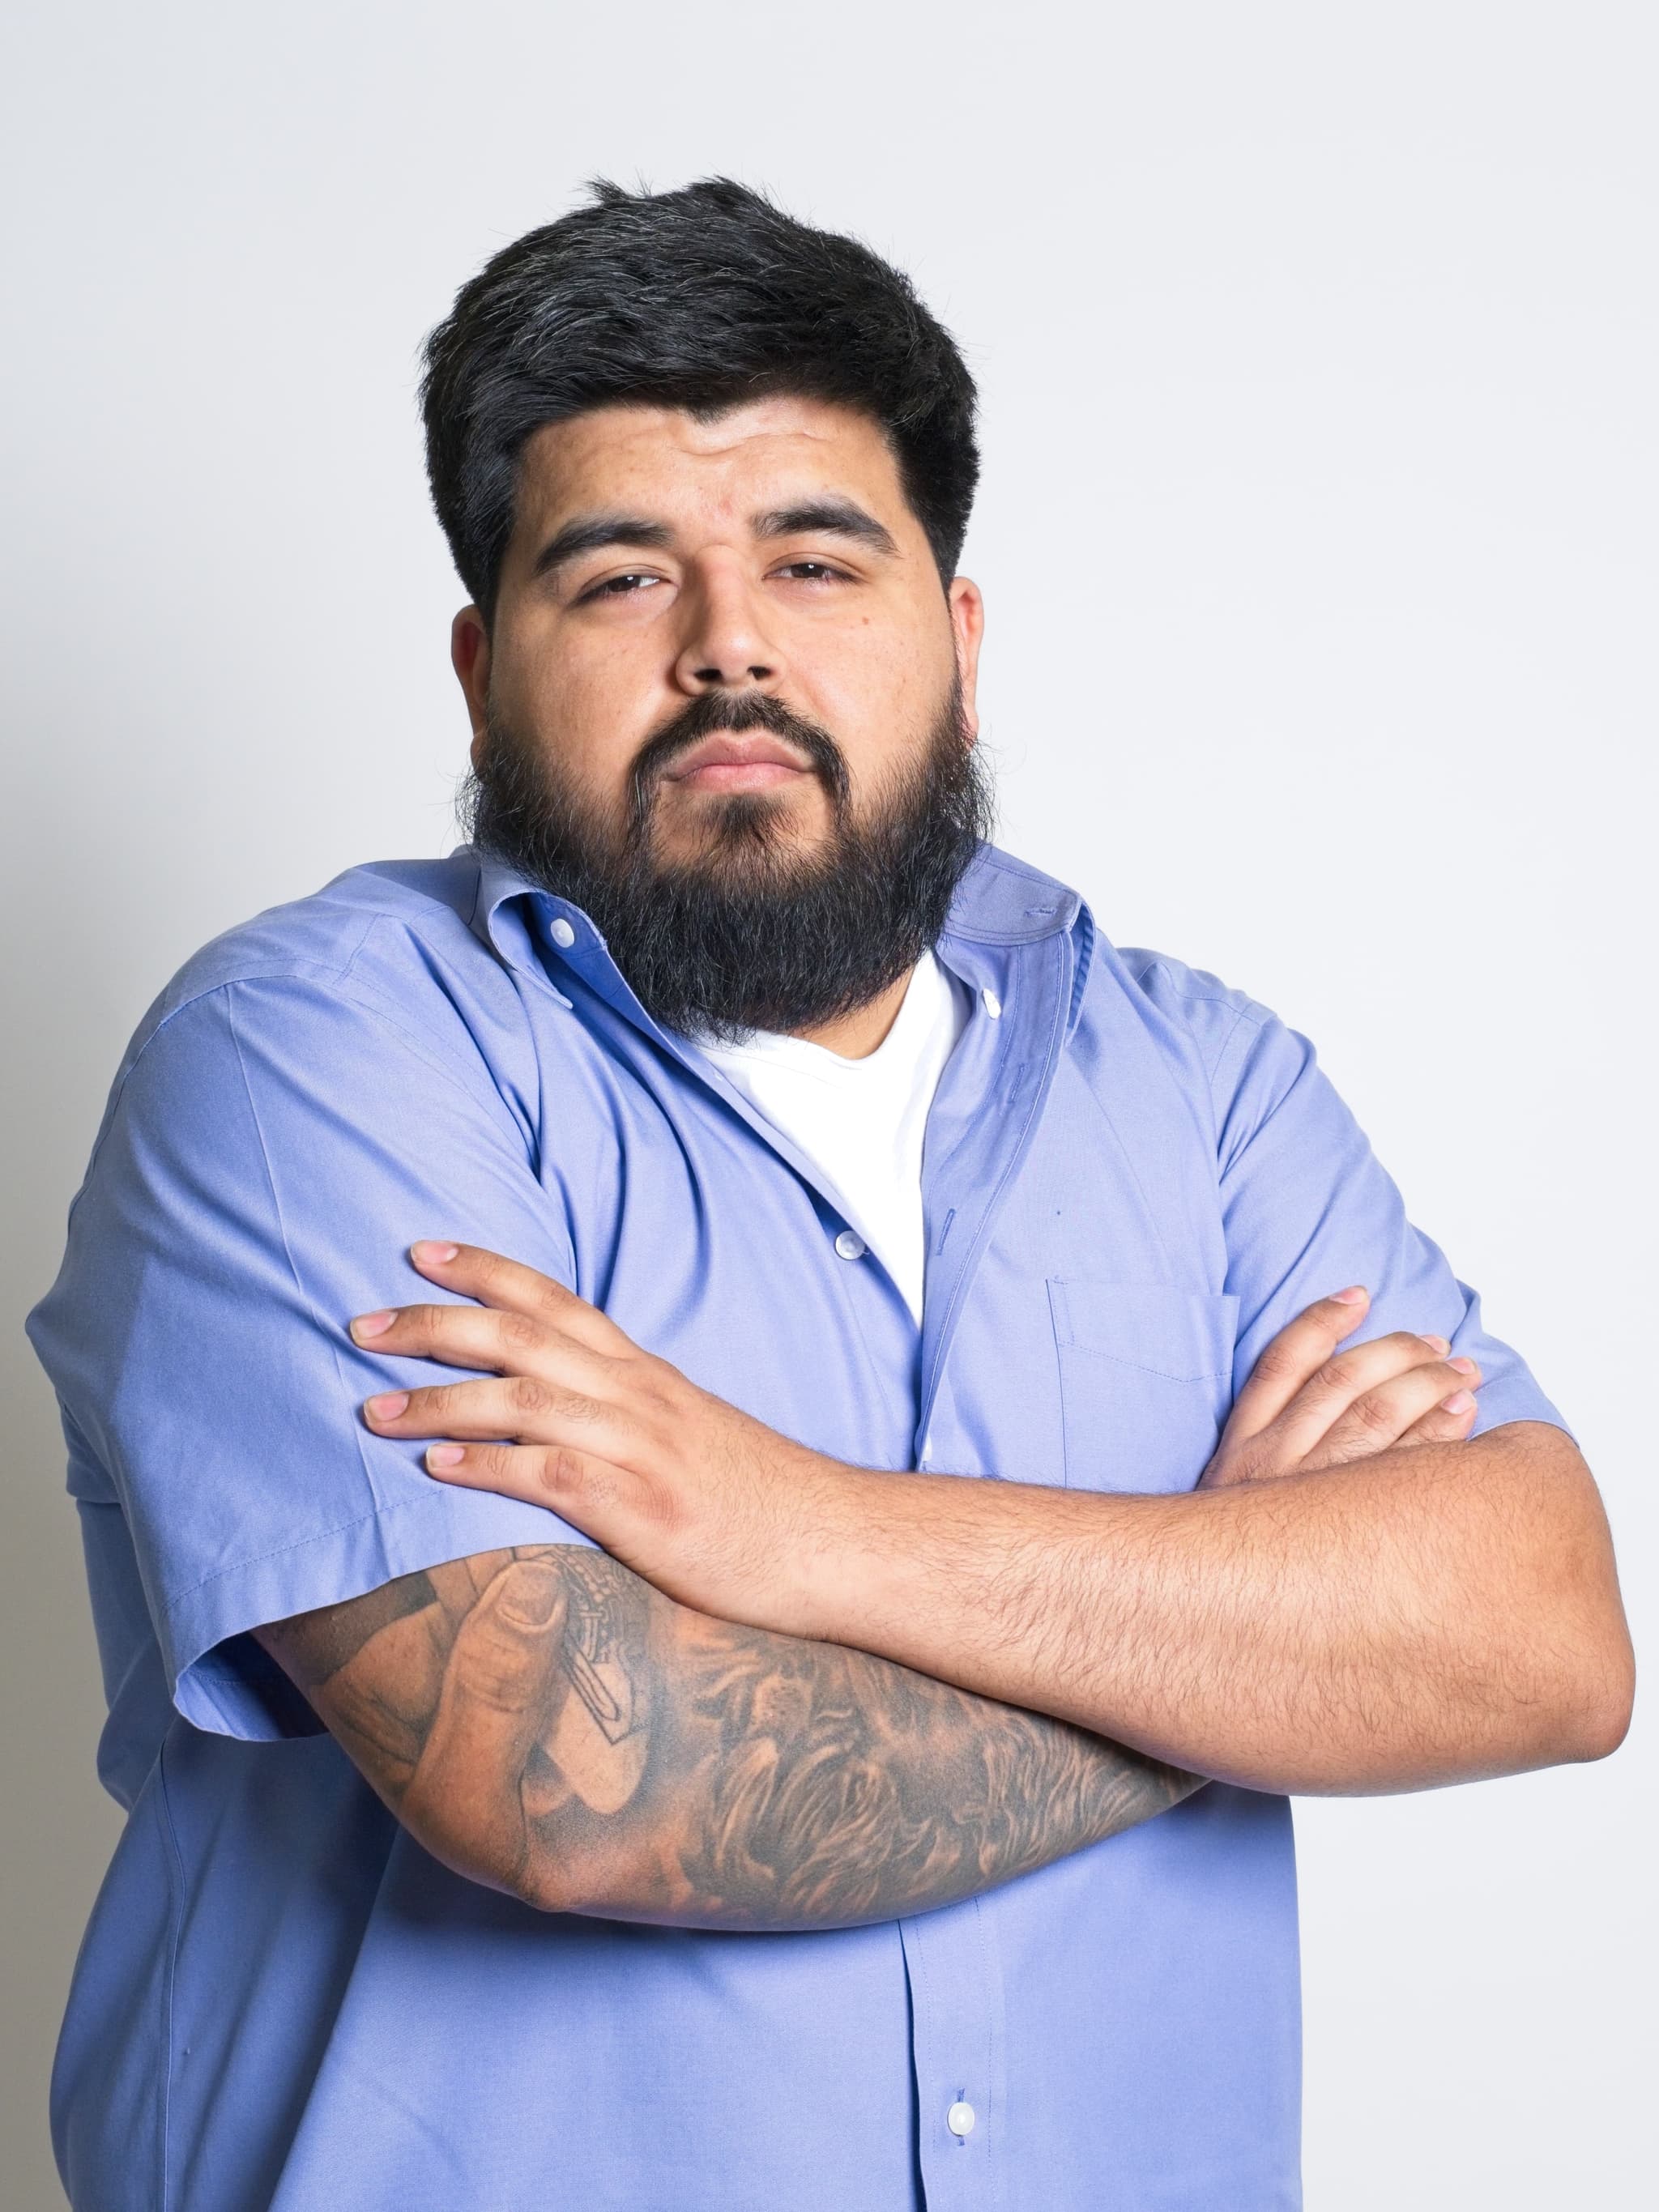
In Jonathan's words
What Our Sales Manager Tells Every Caller
“The biggest discount is bundling home and auto. It is anywhere from 20 to 30 percent, depending on the customer and the premiums on the home or auto. Bundling anything with your auto is always going to be a great idea.”
“The biggest thing we ask everybody is, "When you got this policy, did somebody set it up for you or did you do it yourself? Did they explain what this is?" That allows us to educate and explain why you are paying what you are paying. You are not just giving your money every month to somebody. You are having protection.”
This page is based on a recorded interview with our Sales Manager, Jonathan Sambrano, lightly edited for clarity. Figures are examples he gave and will vary by policy.
We know Oklahoma weather
Wind and hail are the most common claims in the state. We build the policy for what actually happens here, not for the national average.
A real office with licensed people
Everyone who answers the phone passed a state licensing exam. You can walk in at 709 Wall St and sit down with the person who wrote your policy.
With you through every claim
You can file through the carrier app at any hour. We stay involved: explaining what to expect, answering questions as they come up, and following the claim through to resolution.
Three generations in insurance
Elise opened the agency in 2017 after four years working with her father, an agent since 1990. Her grandfather sold life insurance before that.
Good to know
Good to know before you call
- If you own a home you do not live in, even one a family member lives in rent-free, it needs a landlord policy, not a homeowners policy.
- A condo is insured differently: the association covers the building and your policy covers everything inside the walls.
- Carrying at least $300,000 in home liability makes you eligible to add an umbrella policy on top.
Bundle and save
Bundle your home with your auto and save 20 to 30 percent
The same storm that batters your roof can total your car. Insuring both with one local team means one agent who knows your whole situation, and the largest discount we offer.
FAQ
Home insurance questions we hear every week
A standard policy covers the structure, your belongings, liability if someone is hurt on your property, and additional living expenses if the home is unlivable. In Oklahoma we pay close attention to wind and hail, which are the most common claims in the state, and to how your separate wind and hail deductible is set.
Premiums depend on the age, size, roof, and construction of the home, your claims history, your deductibles, and the limits you choose. Rather than a generic estimate, we look at your specific home. Call (405) 253-7879 or use the form and we will put together a real quote.
Most Oklahoma home policies include wind and hail, but the deductible, exclusions, and whether the roof is paid at replacement cost or actual cash value vary significantly. We review these details with every client so the gaps are closed before a storm.
You can file directly through the carrier app or website at any hour. Our office stays involved too: we help you understand what to expect, answer questions, and follow the claim through to resolution. You should not have to navigate it alone.
No. If you do not reside in the home, it needs a landlord policy even when no rent is collected. A homeowners policy on a house you do not live in can become a problem at claim time.
Related coverage
People who look at this also ask about
- Auto InsuranceLiability up to $500,000 per accident, a $0 comprehensive deductible option, and accident forgiveness from day one.Learn more
- Umbrella InsuranceA $1,000,000 to $5,000,000 safety net above your auto and home liability, with attorneys on standby, for about $70 a month.Learn more
- Landlord InsuranceFor any home you own but do not live in, rent or no rent. High liability, rental income protection, and deductibles as low as $1,000.Learn more
Coverage, limits, and discounts vary by policy and are subject to carrier underwriting. A licensed agent will confirm what applies to you.
Get in Touch
Let us make sure your home is actually protected
Buying your first home, switching from a policy that never quite fit, or just want a local review of what you have? Send the form or call. No pressure, no jargon.
Phone
(405) 253-7879
Office Hours
Monday – Thursday, 8:30 AM – 5:30 PM
Friday, 9:00 AM – 5:00 PM
Closed Saturday & Sunday
Request a Free Quote
Fill out the form and we will get back to you within one business day.